Itemized Deductions: A Beginner’s Guide
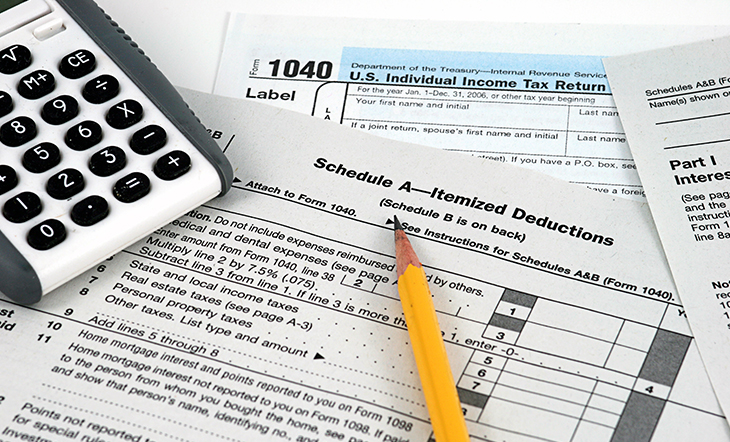
Margaret Mitchell wrote in her bestselling novel, Gone with the wind, “Death and taxes, there’s never any convenient time for any of them.”
We can safely assume that nobody likes to pay tax as they tend to take away a lot of our earnings. But what if there was a way to save up on tax? Itemized deductions, if efficiently incorporated into your tax-return procedure, can save hundreds and thousands of your dollars every year. Here’s a beginners guide to these deductions on when and why should you incorporate them in your tax- returns:
Table of Contents
What are Itemized Deductions?
Itemized deductions are nothing but a list of tax-deductible expenditure that you paid for in a financial year, for which you can receive a tax deduction when you file an income tax return. As per the Internal Revenue Services or IRS, there are two types of deductions: standard deductions and itemized deductions.
A standard deduction is a fixed amount that is pre-decided by the government. An itemized deduction on the other hand, comprises several different expenses that you may have incurred in a financial year.
What Expenses are Included in Itemized Deductions?
There are several expenses that can be capped under itemized deductions. Here are some examples:
- Property Tax: If you own a home, you can add real- estate tax, mortgage premiums, loans points, and property and sales taxes to the list. You can also add city taxes that you pay as part of income tax.
- Medical Expenses: Medical or dental expenses over 10% of the Adjusted Gross Income or AGI can be added. Doctor’s fee, expenses involving diagnosis, treatment and prevention of ailments, nursing home meals, prescription drugs, insurance premiums, medical devices etc. can all be included in medical expenses.
- Self Employment Expenses: If you own a business, you can deduct 50% of your self-employment taxes. If you don’t own a business but work from home, you are also eligible to claim this benefit. As per IRS, you need to have a separate room in your home that can be explicitly used for work purposes. At-home daycare facilities and farmers can also use this provision in their itemized deductions.
- Automobile Expenses: If you use your car or truck for your business, you add a deduction of up to 58 cents per mile for fuel, maintenance, and license costs. You can also add public transport expenses for business related travel if you are able to provide tickets or receipts as proof.
- Educator Expenses: As per IRS rules, if you work for at least 900 hours in a school year, you qualify to be an educator. As an educator, you can add expenses up to $ 250 on your classroom. These include books, computers, and other supply expenses.
- Charitable Contributions: If you have extended financial help to a charity, you can add contributions over 60% of AGI. However, you need proofs like a receipt or acceptance letter from the charity or a copy of your bank statement.
- Interest on investments: This includes broker costs, safe deposit box fees, or advisor consultation fees. However, you can only add expenses up to the amount of profit that you earn via these investments in a financial year. If you don’t make any profit or suffer losses, you are not eligible to add expenses that you may have incurred on your investments.
- Miscellaneous: Other deductions can include local state taxes. Interest on student loans is also considered.
Are There Any Exceptions to Itemized Deductions?
There have been some changes to the tax-returns procedure after the Tax Cuts and Jobs Act was passed in 2018. Tax filing from 2019 will see the following exceptions:
- Expenses like alimony payments, moving costs, and job hunting expenses are no longer considered in itemized deductions.
- You cannot claim losses due to a natural disaster.
- Cosmetic procedures are not covered. There is still lingering confusion about surgeries that fall under the spectrum of both cosmetic and health treatment. It is best to discuss these differences with a financial advisor before you add them to your list of itemized deductions.
- Only medical expenses that are at least 7.5 % higher than your Gross Adjusted Income can be added.
How to Claim Itemized Deductions?
There’s a simple procedure to follow to claim these deductions:
- Download Form no. 1040 from the official IRS website.
- Make a list of all your itemized deduction and follow Schedule A (given on IRS website) to add up all your itemized deductions.
If you are a farmer, you should use Schedule F. - You will have to specify on your form whether you are opting for standard or itemized deduction.
When Should You Opt for Itemized Deductions?
Itemized deductions are only useful if they are valued higher than standard deductions. The idea is to save as much tax as you can. If the total cost of your itemized deductions is less than your standard deduction, you should go ahead with the latter. Here are the standard deduction values for 2019:
- For couples who are filing their income tax as ‘Married filing jointly’ the standard deduction cap is $24,400.
- For head of households, the value is $18,350.
- For all other who don’t fall in these two categories, for example, unmarried individuals or a couple filing separately, the limit is $12,200.
However, there are some scenarios where you may not be eligible for standard deductions. For example:
- If you are filing your tax return for a period of less than 12 months.
- If you are a non-resident alien or have a dual-status citizenship.
- If you are married and your spouse itemizes their deductions and you are filing your tax returns as ‘married filing separately’.
- If you are filing as a trust: estate, common trust funds, and partnerships.
You must always carefully access which of the two give you a more significant tax relief. This could also be different for every financial year, depending on where you spend your money.
To Sum it Up
The income tax filing procedure has seen a few new trends this year. Before the Tax Cuts and Jobs Act, 30 % of Americans used itemized deduction to save taxes; whereas, the remaining 70% opted for standard deductions. Experts predict that after the implementation of the Act, over 90% of Americans will use standard deductions. Itemized deductions are now useful to primarily those who may have bought a home, as real estate expenses have the potential to cross the government’s standard deduction limits.
Do you need help in filing your tax? Not sure which of the two deductions to choose from? Reach out to financial advisors to understand which is better and why!

Related Article
8 min read
07 Sep 2026
The Need for Honest Conversation with Your Financial Advisor
Financial planning is often associated with investment returns, retirement projections, and tax strategies. Yet one of the biggest factors determining whether a financial plan succeeds has nothing to do with markets or interest rates. It is the quality of communication between you and your financial advisor. Many professionals spend decades building wealth and making thoughtful […]
10 min read
14 Aug 2026
How to Prepare for a Meeting With Your Financial Advisor
First meetings are important. Whether you are going for a job interview, a first date, or meeting your interior decorator for the first time, starting on the right foot is essential. It gives you an opportunity to get to know the person in front of you and decide whether you want to take the relationship […]
12 min read
11 Aug 2026
Why You Should Continue Meeting With Your Financial Advisor
Most people meet with their financial advisor far less as the years go by, and the drop-off is steepest right when it should be climbing. Early on, when you are setting things up, you talk often. The plan gets built, the accounts get funded, and then contact thins out. A meeting a year becomes a […]
10 min read
11 Jun 2026
Is it Wise to Put All Your Money With One Financial Advisor?
There is a saying that there is always room for one more. That might work for celebrations, but when it comes to your money, it is not quite the same story. Financial planning is not always about adding more or even less, for that matter. It is all about getting the balance right. When you […]
More From Author
14 min read
23 Jan 2024
How to Determine If Your Financial Advisor Is Doing a Good Job Each Year
The decision to hire a financial advisor is a prudent move. Seeking professional advice can provide valuable insights and a roadmap to achieve your financial goals with strategic planning. But the world of financial advice is crowded. While some advisors bring qualifications, expertise, and a commitment to your financial well-being, others may fall short of […]
10 min read
14 Aug 2026
How to Prepare for a Meeting With Your Financial Advisor
First meetings are important. Whether you are going for a job interview, a first date, or meeting your interior decorator for the first time, starting on the right foot is essential. It gives you an opportunity to get to know the person in front of you and decide whether you want to take the relationship […]
3 min read
26 Jul 2019
Best Retirement Calculators to plan Retirement
It is said that a goal without a plan is just a wish. This holds true even for retirement planning. You dream of a peaceful retired life. To achieve that you must plan for your golden years well in time. Various retirement tools make your task easier. For example, a retirement calculator helps you calculate […]
9 min read
27 Jan 2022
Questions to Ask Your Financial Advisor
Searching for a financial advisor can be challenging. You may feel overwhelmed in trying to get the decision right, since the advisor you choose will be in charge of helping you grow and manage your finances. It is recommended that you find an advisor who you can trust to communicate consistently with you, one who […]
Find & Compare Top Financial
Advisors in your area
Get Started
Popular Posts
Categories
- Business Finance (1)
- Education Planning (31)
- Estate Planning (31)
- Financial Advisor (1)
- Financial Advisor Guide (56)
- Financial Planning (139)
- Investment Management (101)
- Personal Finance (16)
- Retirement Planning (141)
- Uncategorized (2)
Subscribe to our
newsletter & get helpful
financial tips.
The blog articles on this website are provided for general educational and informational purposes only, and no content included is intended to be used as financial or legal advice. A professional financial advisor should be consulted prior to making any investment decisions. Each person’s financial situation is unique, and your advisor would be able to provide you with the financial information and advice related to your financial situation.