The Need for Honest Conversation with Your Financial Advisor
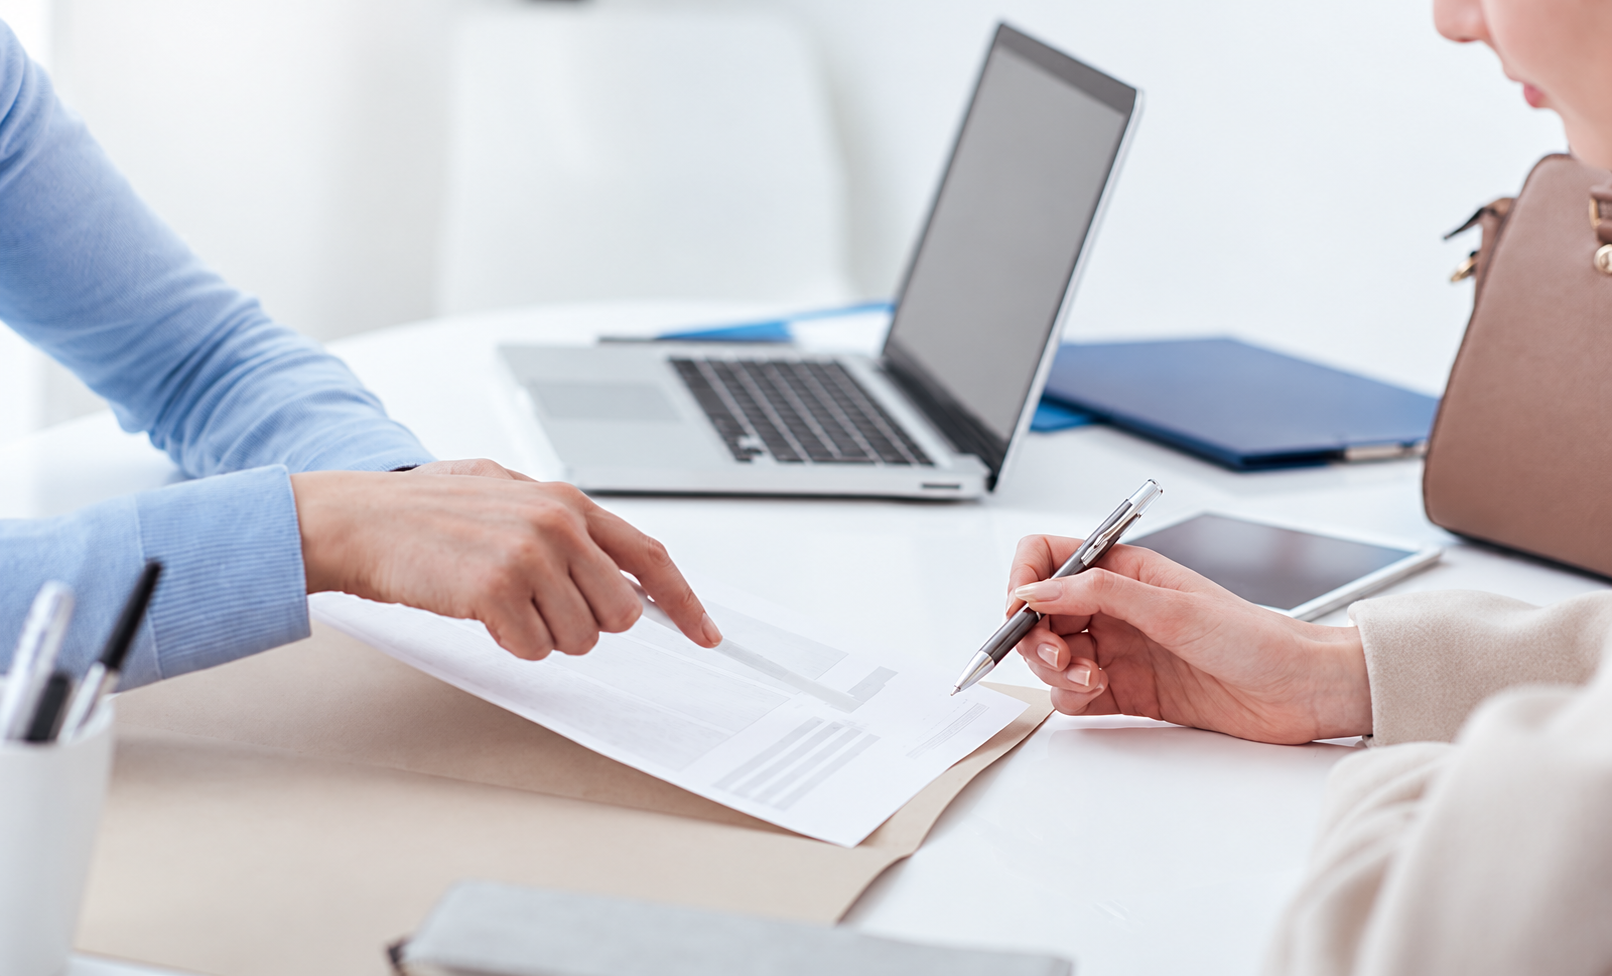
Financial planning is often associated with investment returns, retirement projections, and tax strategies. Yet one of the biggest factors determining whether a financial plan succeeds has nothing to do with markets or interest rates. It is the quality of communication between you and your financial advisor.
Many professionals spend decades building wealth and making thoughtful financial decisions. Ironically, in conversations with their advisor, they may unintentionally leave out information that matters as much as their portfolio balance.
A financial plan is built on assumptions. Your expected retirement age, lifestyle goals, healthcare costs, family responsibilities, income sources, and spending habits all shape the recommendations your advisor makes. If those assumptions are incomplete or inaccurate, even technically sound advice may no longer fit your circumstances.
Table of Contents
- Understand why even excellent advice can miss the mark without the full picture
- What to discuss with your financial advisor?
- Approach difficult conversations by focusing on outcomes, not explanations
- How to build trust with a financial advisor?
- The plan is only as good as the conversation behind it
- Frequently asked questions about being honest with your financial advisor
Understand why even excellent advice can miss the mark without the full picture
Think of a financial plan as the blueprint for building a house. The architect may be exceptionally skilled, but if the land survey is incorrect, the blueprint will be flawed.
An advisor analyses the available information and builds recommendations around it. Retirement income strategies, tax planning, portfolio allocation, insurance needs, and estate planning all depend on the facts you provide. Missing information changes the assumptions behind those recommendations.
Suppose your advisor believes you plan to retire at 67. If you quietly hope to retire at 60 but never mention it, your investment strategy, savings targets, withdrawal plan, and Social Security timing may be designed around the wrong objective. Similarly, if you are supporting elderly parents, planning to fund a grandchild’s education, or expecting to purchase a second home in retirement, those future commitments deserve a place in your financial plan.
What to discuss with your financial advisor?
One of the most common questions people ask is what they should actually tell their financial advisor. The short answer is far more than your income, investments, or retirement savings.
A good financial advisor needs to understand your finances, but they also need to understand your life. A retirement strategy built for someone who wants to travel the world will look very different from one designed for someone planning to support aging parents or leave a substantial legacy. Think of anything that could change the way you earn, spend, save, or invest over the next ten or twenty years. Those are the conversations worth having.
This includes your ideal retirement age even if it seems ambitious today, the lifestyle you hope to enjoy in retirement, plans to move or downsize, financial support you provide or expect to provide to children or aging parents, health concerns that could affect future expenses, business interests or consulting income after leaving full-time work, stock options or deferred compensation, expected inheritances, charitable giving plans, and major purchases you expect to make in the coming years.
Just as importantly, do not leave out information because it feels too personal or unrelated to investing. High-interest debt, investment accounts held elsewhere, rental properties, private investments, divorce, remarriage, changes in employment, concentrated employer stock, or plans to help children financially can all influence the advice you receive. These conversations often uncover planning opportunities that might otherwise be missed.
A simple rule: if it could change your financial future, it deserves a place in the conversation, even if it has not happened yet.
Approach difficult conversations by focusing on outcomes, not explanations
Many clients find it hard to raise uncomfortable subjects with their advisor. The approach is simpler than most expect. Focus on outcomes rather than explanations.
Instead of worrying about how to justify an expensive lifestyle purchase, explain how that purchase changes your future plans. Instead of dwelling on an investment loss, discuss how you want to approach investing going forward. If your retirement timeline has changed because work has become less fulfilling or because family priorities have shifted, say so directly.
Some of the most productive conversations start with statements like these:
- “I am beginning to think I want to retire earlier than we originally planned.”
- “We are considering helping our daughter buy her first home.”
- “I may want to relocate within five years.”
- “My spending has increased more than I expected.”
These conversations let your advisor adjust the plan before small changes become bigger problems. Financial advisor communication should not revolve solely around investment performance. Life events deserve equal attention because they often affect long-term outcomes more than short-term market movements.
Ask these questions at every review to get more from the conversation
Annual reviews often focus on portfolio returns. While performance matters, the more valuable conversation usually focuses on whether your financial plan still reflects your life.
Consider raising questions like these during your review meetings:
- Which assumptions in my financial plan concern you most?
- If I retired five years earlier, how would my plan change?
- What risks do you believe I am underestimating?
- Which parts of my retirement plan are most sensitive to inflation?
- Have recent tax law changes affected my long-term strategy?
- Should my investment allocation change given my current circumstances?
- What information would help you provide better advice?
- Which financial decisions should I avoid making before our next meeting?
These questions focus less on predicting markets and more on improving decision-making, which is where long-term financial planning creates the most value.
How often to meet your financial advisor
The right frequency depends on the complexity of your finances, your stage of life, and how often your circumstances change. For most professionals approaching retirement, at least one comprehensive annual review is essential. If your finances involve a business, stock-based compensation, or multiple income streams, meeting every six months may be more appropriate.
Beyond scheduled reviews, consider reaching out when something material changes. A promotion, a change in retirement plans, marriage or divorce, the birth of a grandchild, the sale of a business, a significant inheritance, a major property purchase, a health event, or a shift in long-term priorities can all affect your income, taxes, investment strategy, or retirement timeline. Reviewing your plan soon after these changes helps ensure your financial decisions stay aligned with your goals.
How to build trust with a financial advisor?
Trust is built through open communication, realistic expectations, and a shared understanding of your goals, not solely through investment performance.
A good advisor should help you understand what they recommend and why. Their explanations should cover the assumptions behind their recommendations, the potential benefits and drawbacks of different options, the risks involved in any long-term strategy, their fees and how they are compensated, and how your plan may need to adapt as your circumstances change.
Trust also requires your active participation. An advisor can provide relevant advice only when they have current, accurate information. If your income changes, your retirement plans shift, or your priorities evolve, your advisor should know as soon as possible. View your advisor as someone you talk with regularly, not someone you visit once a year to review performance.
No advisor can eliminate uncertainty. Markets fluctuate, tax laws change, and unexpected events occur. A trustworthy advisor acknowledges these uncertainties, explains how they affect your plan, and helps you make informed decisions rather than offering reassurance they cannot back up.
The plan is only as good as the conversation behind it
Before your next meeting, consider whether any of the following have changed since you last spoke with your advisor:
Employment or compensation, bonuses or stock options, new investment accounts, private investments, pension updates, expected inheritances, major purchases or property transactions, family members who rely on you financially, healthcare concerns, insurance coverage, estate planning updates, charitable giving goals, retirement timeline, expected consulting or part-time income, tax changes affecting your household, business ownership, and long-term care planning.
Reviewing this list before each meeting helps ensure your advisor is working with current information rather than outdated assumptions. Even minor changes today can affect your retirement strategy, tax planning, or investment decisions over time.
A financial plan is only as effective as the conversations behind it. The more openly you communicate, the easier it becomes for your advisor to anticipate challenges, identify opportunities, and keep your plan aligned with your goals. If you’re looking for advice, consider using our advisor directory to connect with experienced financial professionals near you.
Frequently asked questions about being honest with your financial advisor
1. Can I contact my financial advisor between scheduled review meetings?
Yes. You don’t have to wait for your next annual or semi-annual review if something important changes. A new job, an inheritance, a major purchase, or even a shift in your retirement goals can affect your financial plan. Keeping your advisor informed throughout the year lets them recommend adjustments before small changes become bigger financial challenges.
2. Should I tell my financial advisor about financial goals that I’m still unsure about?
Absolutely. Even if your plans aren’t final, discussing them helps your advisor prepare for different scenarios. Whether you’re considering early retirement, relocating, starting a business, or helping your children financially, exploring these possibilities early often leads to more flexible and informed planning.
3. What if I disagree with my financial advisor’s recommendation?
A healthy advisor-client relationship should encourage questions and discussion. Ask your advisor to explain the assumptions behind their recommendation, the potential risks, and any alternative approaches. Understanding the reasoning behind a strategy helps you make informed decisions with greater confidence.
4. How should I prepare for a meeting with my financial advisor?
Before your meeting, review any significant changes to your finances or personal circumstances. Gather relevant documents, note any questions you want to discuss, and think about whether your priorities or long-term goals have changed since your last conversation. Being prepared helps make the meeting more productive for both you and your advisor.

Related Article
10 min read
14 Aug 2026
How to Prepare for a Meeting With Your Financial Advisor
First meetings are important. Whether you are going for a job interview, a first date, or meeting your interior decorator for the first time, starting on the right foot is essential. It gives you an opportunity to get to know the person in front of you and decide whether you want to take the relationship […]
12 min read
11 Aug 2026
Why You Should Continue Meeting With Your Financial Advisor
Most people meet with their financial advisor far less as the years go by, and the drop-off is steepest right when it should be climbing. Early on, when you are setting things up, you talk often. The plan gets built, the accounts get funded, and then contact thins out. A meeting a year becomes a […]
10 min read
11 Jun 2026
Is it Wise to Put All Your Money With One Financial Advisor?
There is a saying that there is always room for one more. That might work for celebrations, but when it comes to your money, it is not quite the same story. Financial planning is not always about adding more or even less, for that matter. It is all about getting the balance right. When you […]
10 min read
11 May 2026
What is the Cost of Hiring a Financial Advisor?
Hiring a financial advisor does not have to cost you an arm and a leg. In fact, looking at the cost in isolation is a bit misleading. While there is a fee involved, what you get in return is so much more than what you pay. The cost of a financial advisor is subjective and […]
More From Author
14 min read
23 Jan 2024
How to Determine If Your Financial Advisor Is Doing a Good Job Each Year
The decision to hire a financial advisor is a prudent move. Seeking professional advice can provide valuable insights and a roadmap to achieve your financial goals with strategic planning. But the world of financial advice is crowded. While some advisors bring qualifications, expertise, and a commitment to your financial well-being, others may fall short of […]
10 min read
14 Aug 2026
How to Prepare for a Meeting With Your Financial Advisor
First meetings are important. Whether you are going for a job interview, a first date, or meeting your interior decorator for the first time, starting on the right foot is essential. It gives you an opportunity to get to know the person in front of you and decide whether you want to take the relationship […]
3 min read
26 Jul 2019
Best Retirement Calculators to plan Retirement
It is said that a goal without a plan is just a wish. This holds true even for retirement planning. You dream of a peaceful retired life. To achieve that you must plan for your golden years well in time. Various retirement tools make your task easier. For example, a retirement calculator helps you calculate […]
9 min read
27 Jan 2022
Questions to Ask Your Financial Advisor
Searching for a financial advisor can be challenging. You may feel overwhelmed in trying to get the decision right, since the advisor you choose will be in charge of helping you grow and manage your finances. It is recommended that you find an advisor who you can trust to communicate consistently with you, one who […]
Find & Compare Top Financial
Advisors in your area
Get Started
Popular Posts
Categories
- Business Finance (1)
- Education Planning (31)
- Estate Planning (31)
- Financial Advisor (1)
- Financial Advisor Guide (56)
- Financial Planning (139)
- Investment Management (101)
- Personal Finance (16)
- Retirement Planning (141)
- Uncategorized (2)
Subscribe to our
newsletter & get helpful
financial tips.
The blog articles on this website are provided for general educational and informational purposes only, and no content included is intended to be used as financial or legal advice. A professional financial advisor should be consulted prior to making any investment decisions. Each person’s financial situation is unique, and your advisor would be able to provide you with the financial information and advice related to your financial situation.